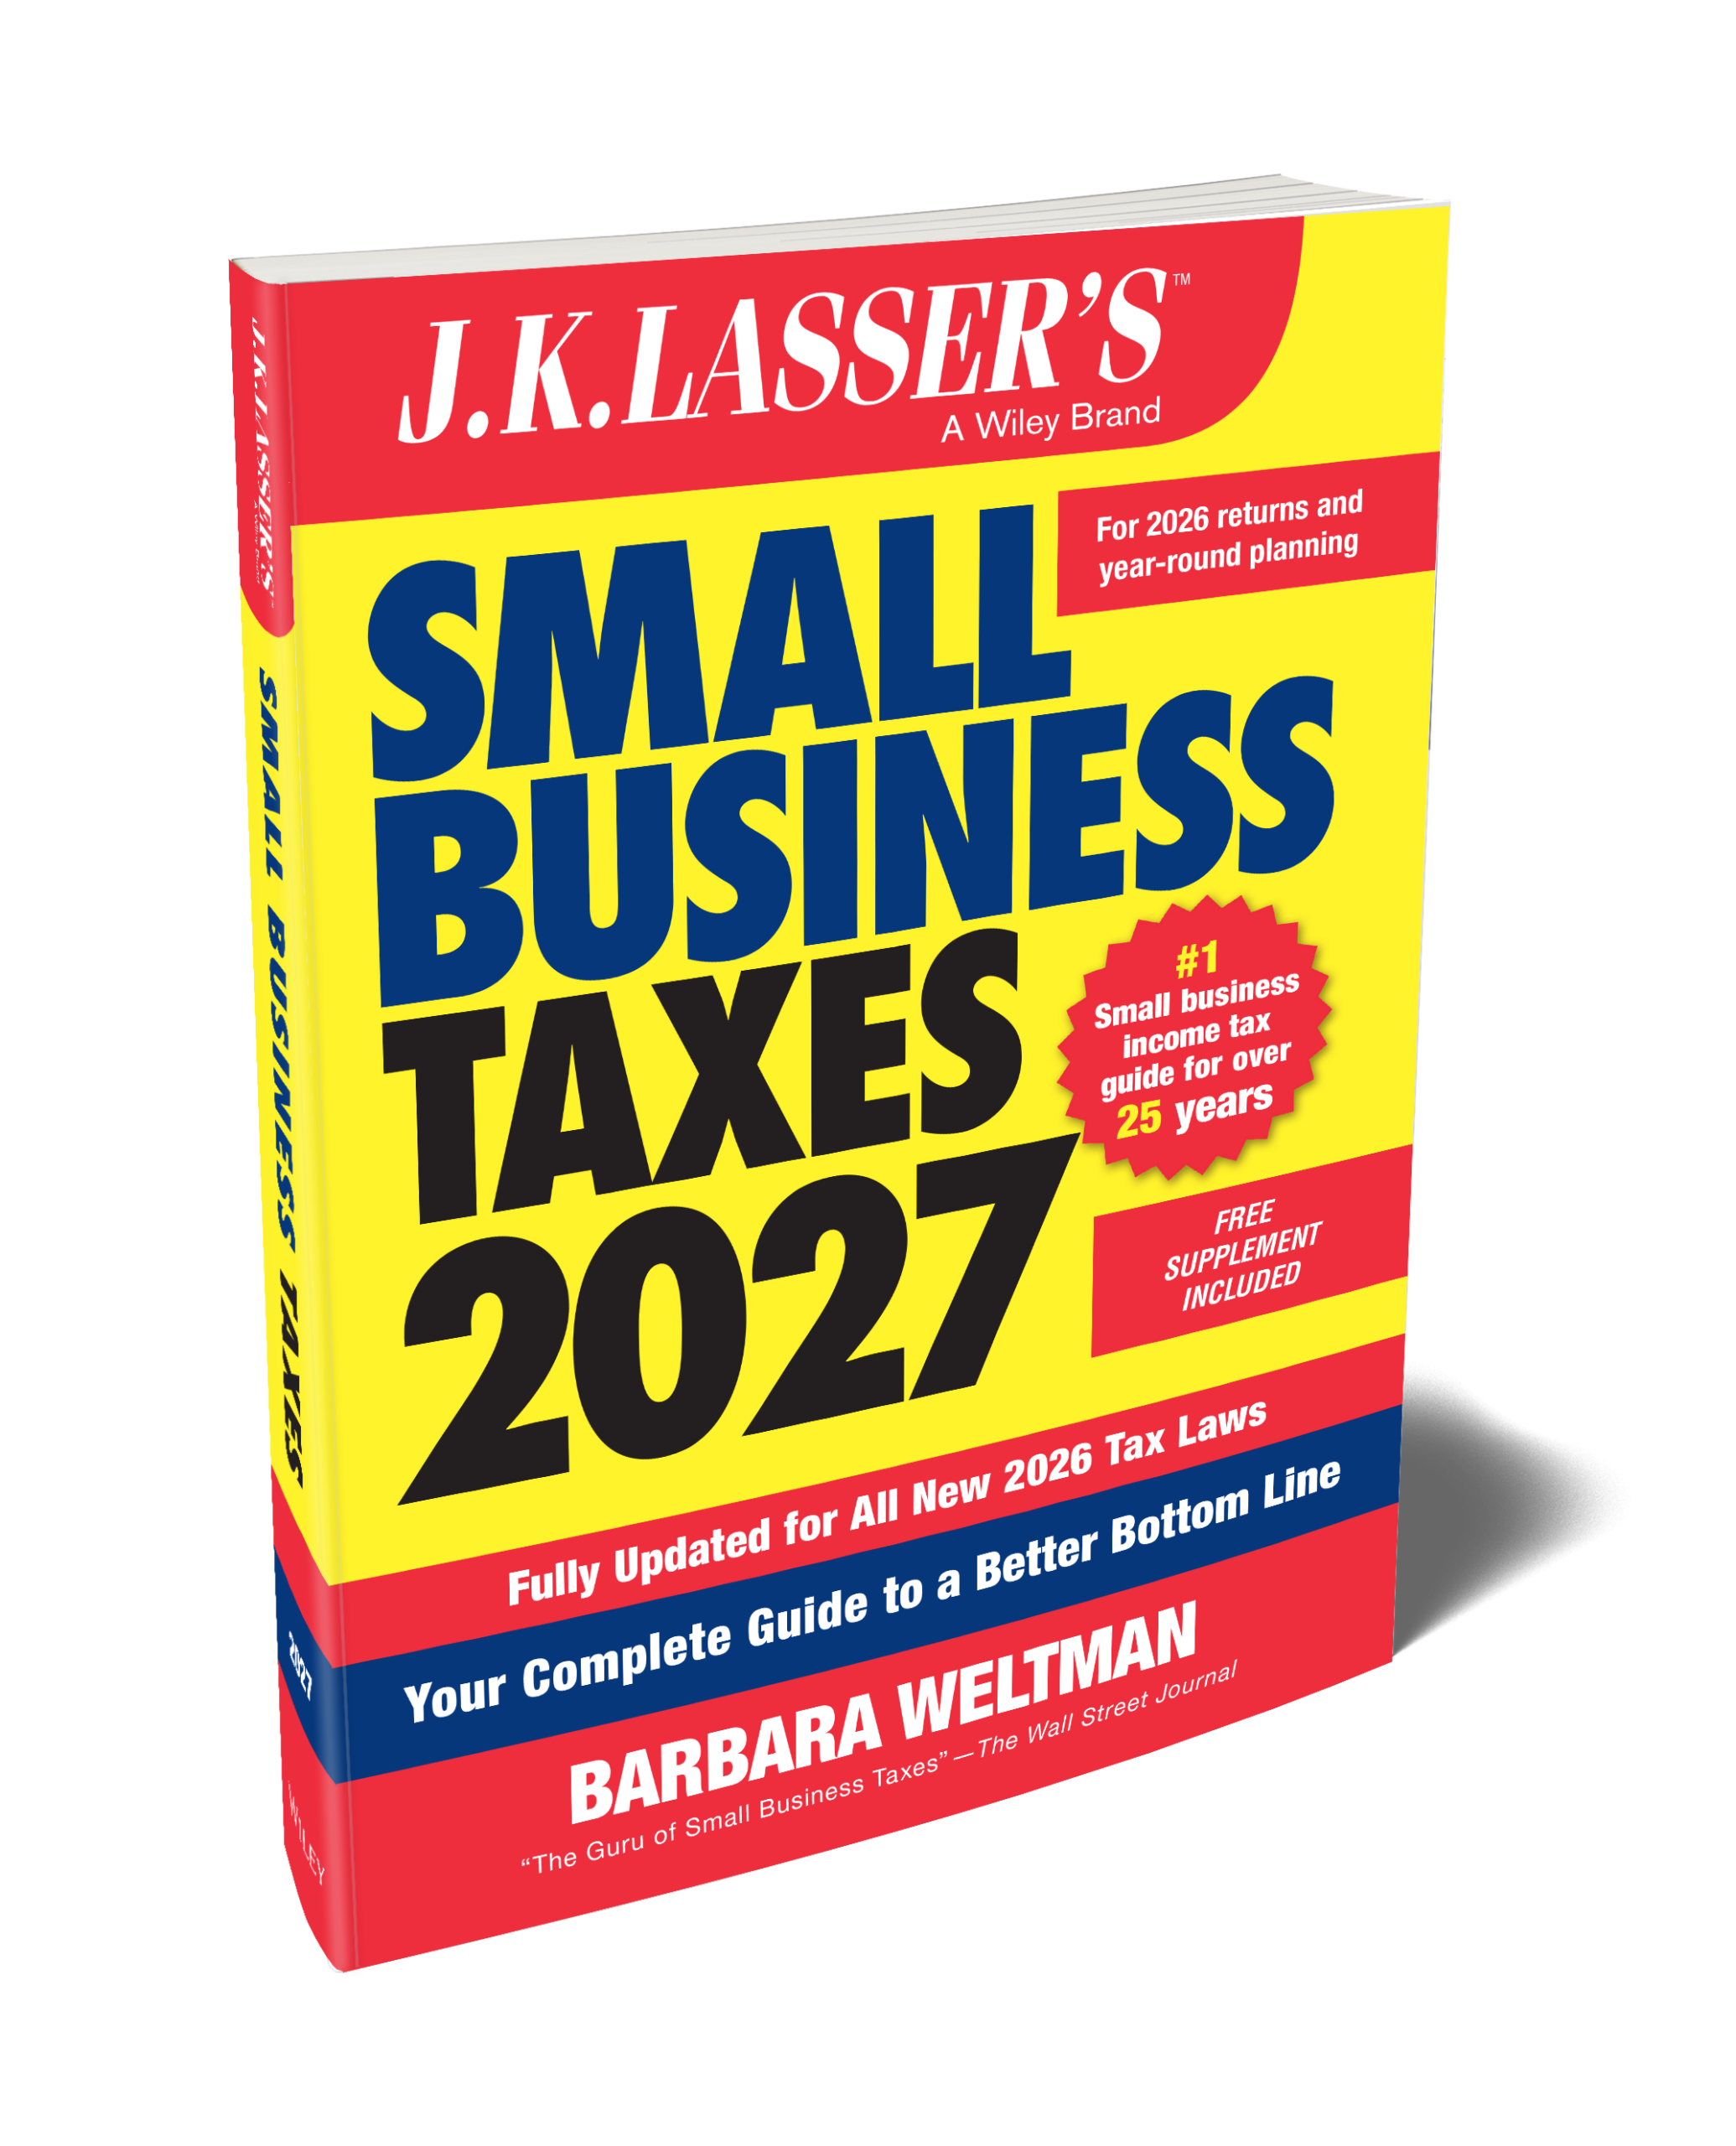
$25.00 
Learn more
For 2018 through 2025, the miscellaneous itemized deduction for investment-related costs is not deductible. Before 2018, these amounts were subject to the 2%-of-adjusted-gross-income floor. After 2026, such amounts may be deductible (assuming total costs exceed the 2% floor).
Income earned by a person before death but taxable to an estate or heir who receives it.
Copyright © 2000- John Wiley & Sons, Inc., or related companies. All rights reserved. Please read our Privacy Policy.