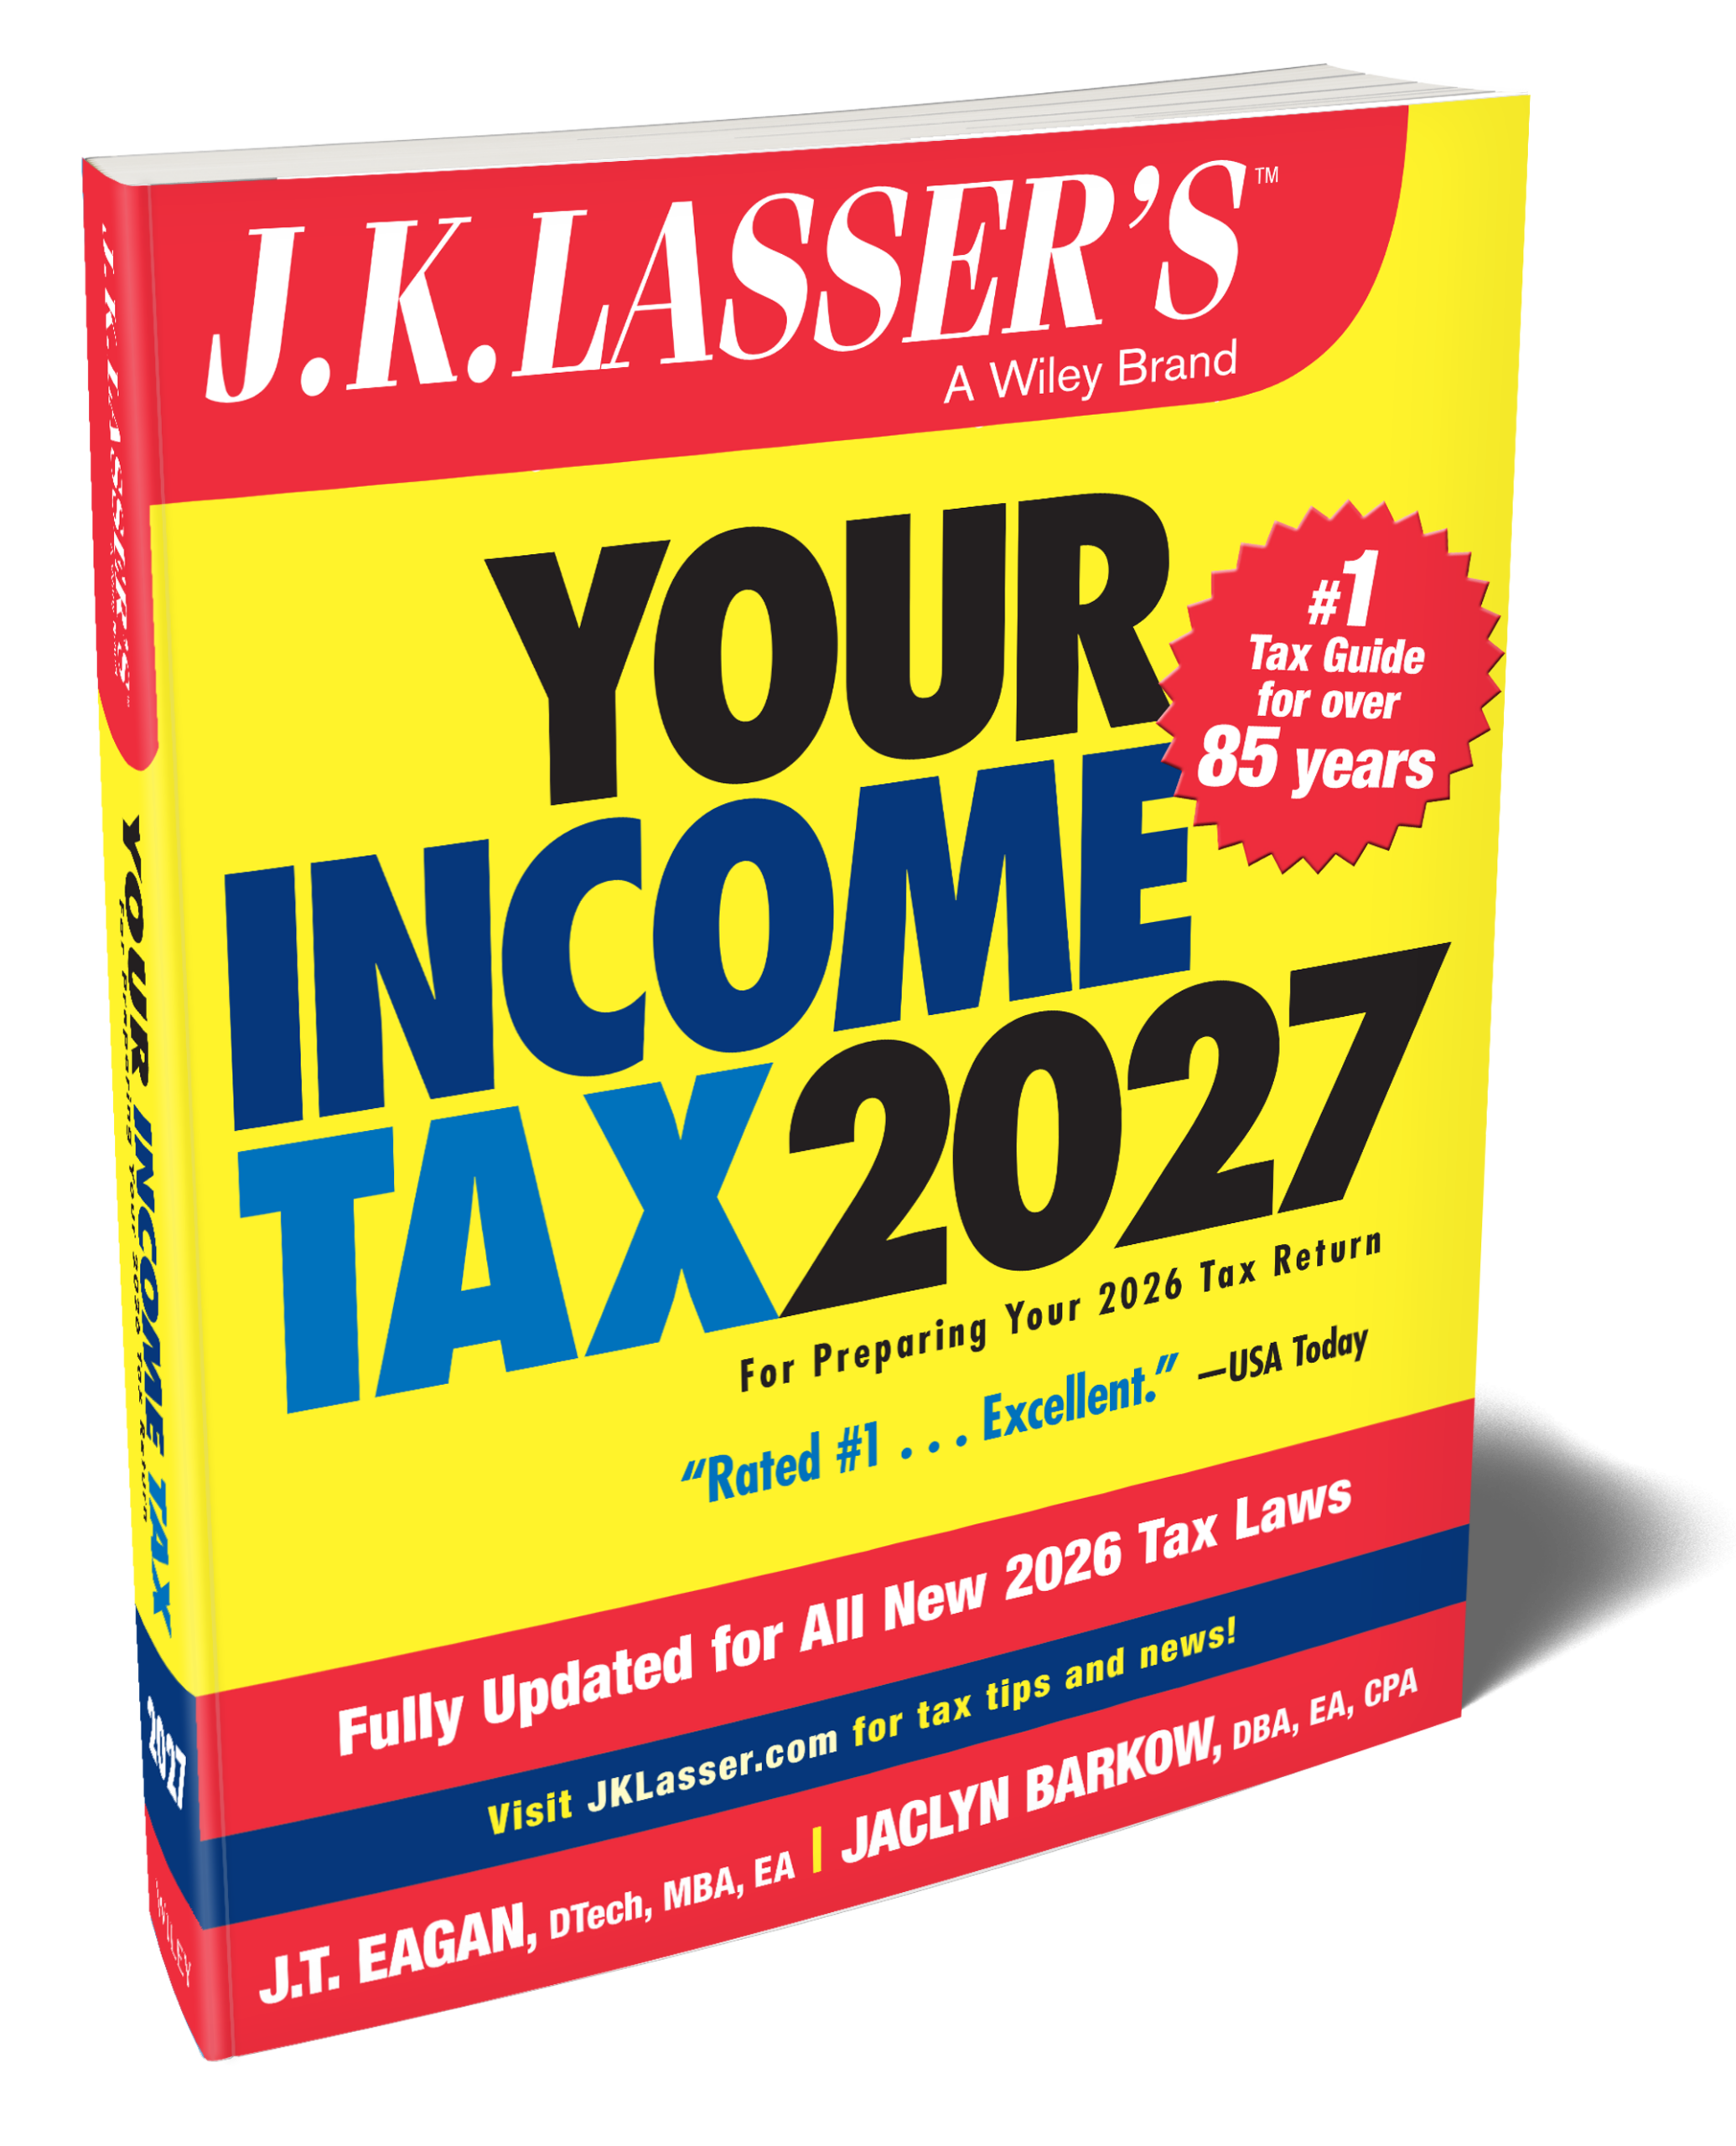
$27.00 
Learn more
The exclusion of up to $5,000 for death benefits no longer applies. It had applied only for employees who died before August 21, 1996. Only a death gratuity paid to a survivor of a member of the Armed Forces continues to be excludable from gross income.
An arrangement under which one person transfers legal ownership of assets to another person or corporation (the trustee) for the benefit of one or more third persons (beneficiaries).
Copyright © 2000- John Wiley & Sons, Inc., or related companies. All rights reserved. Please read our Privacy Policy.