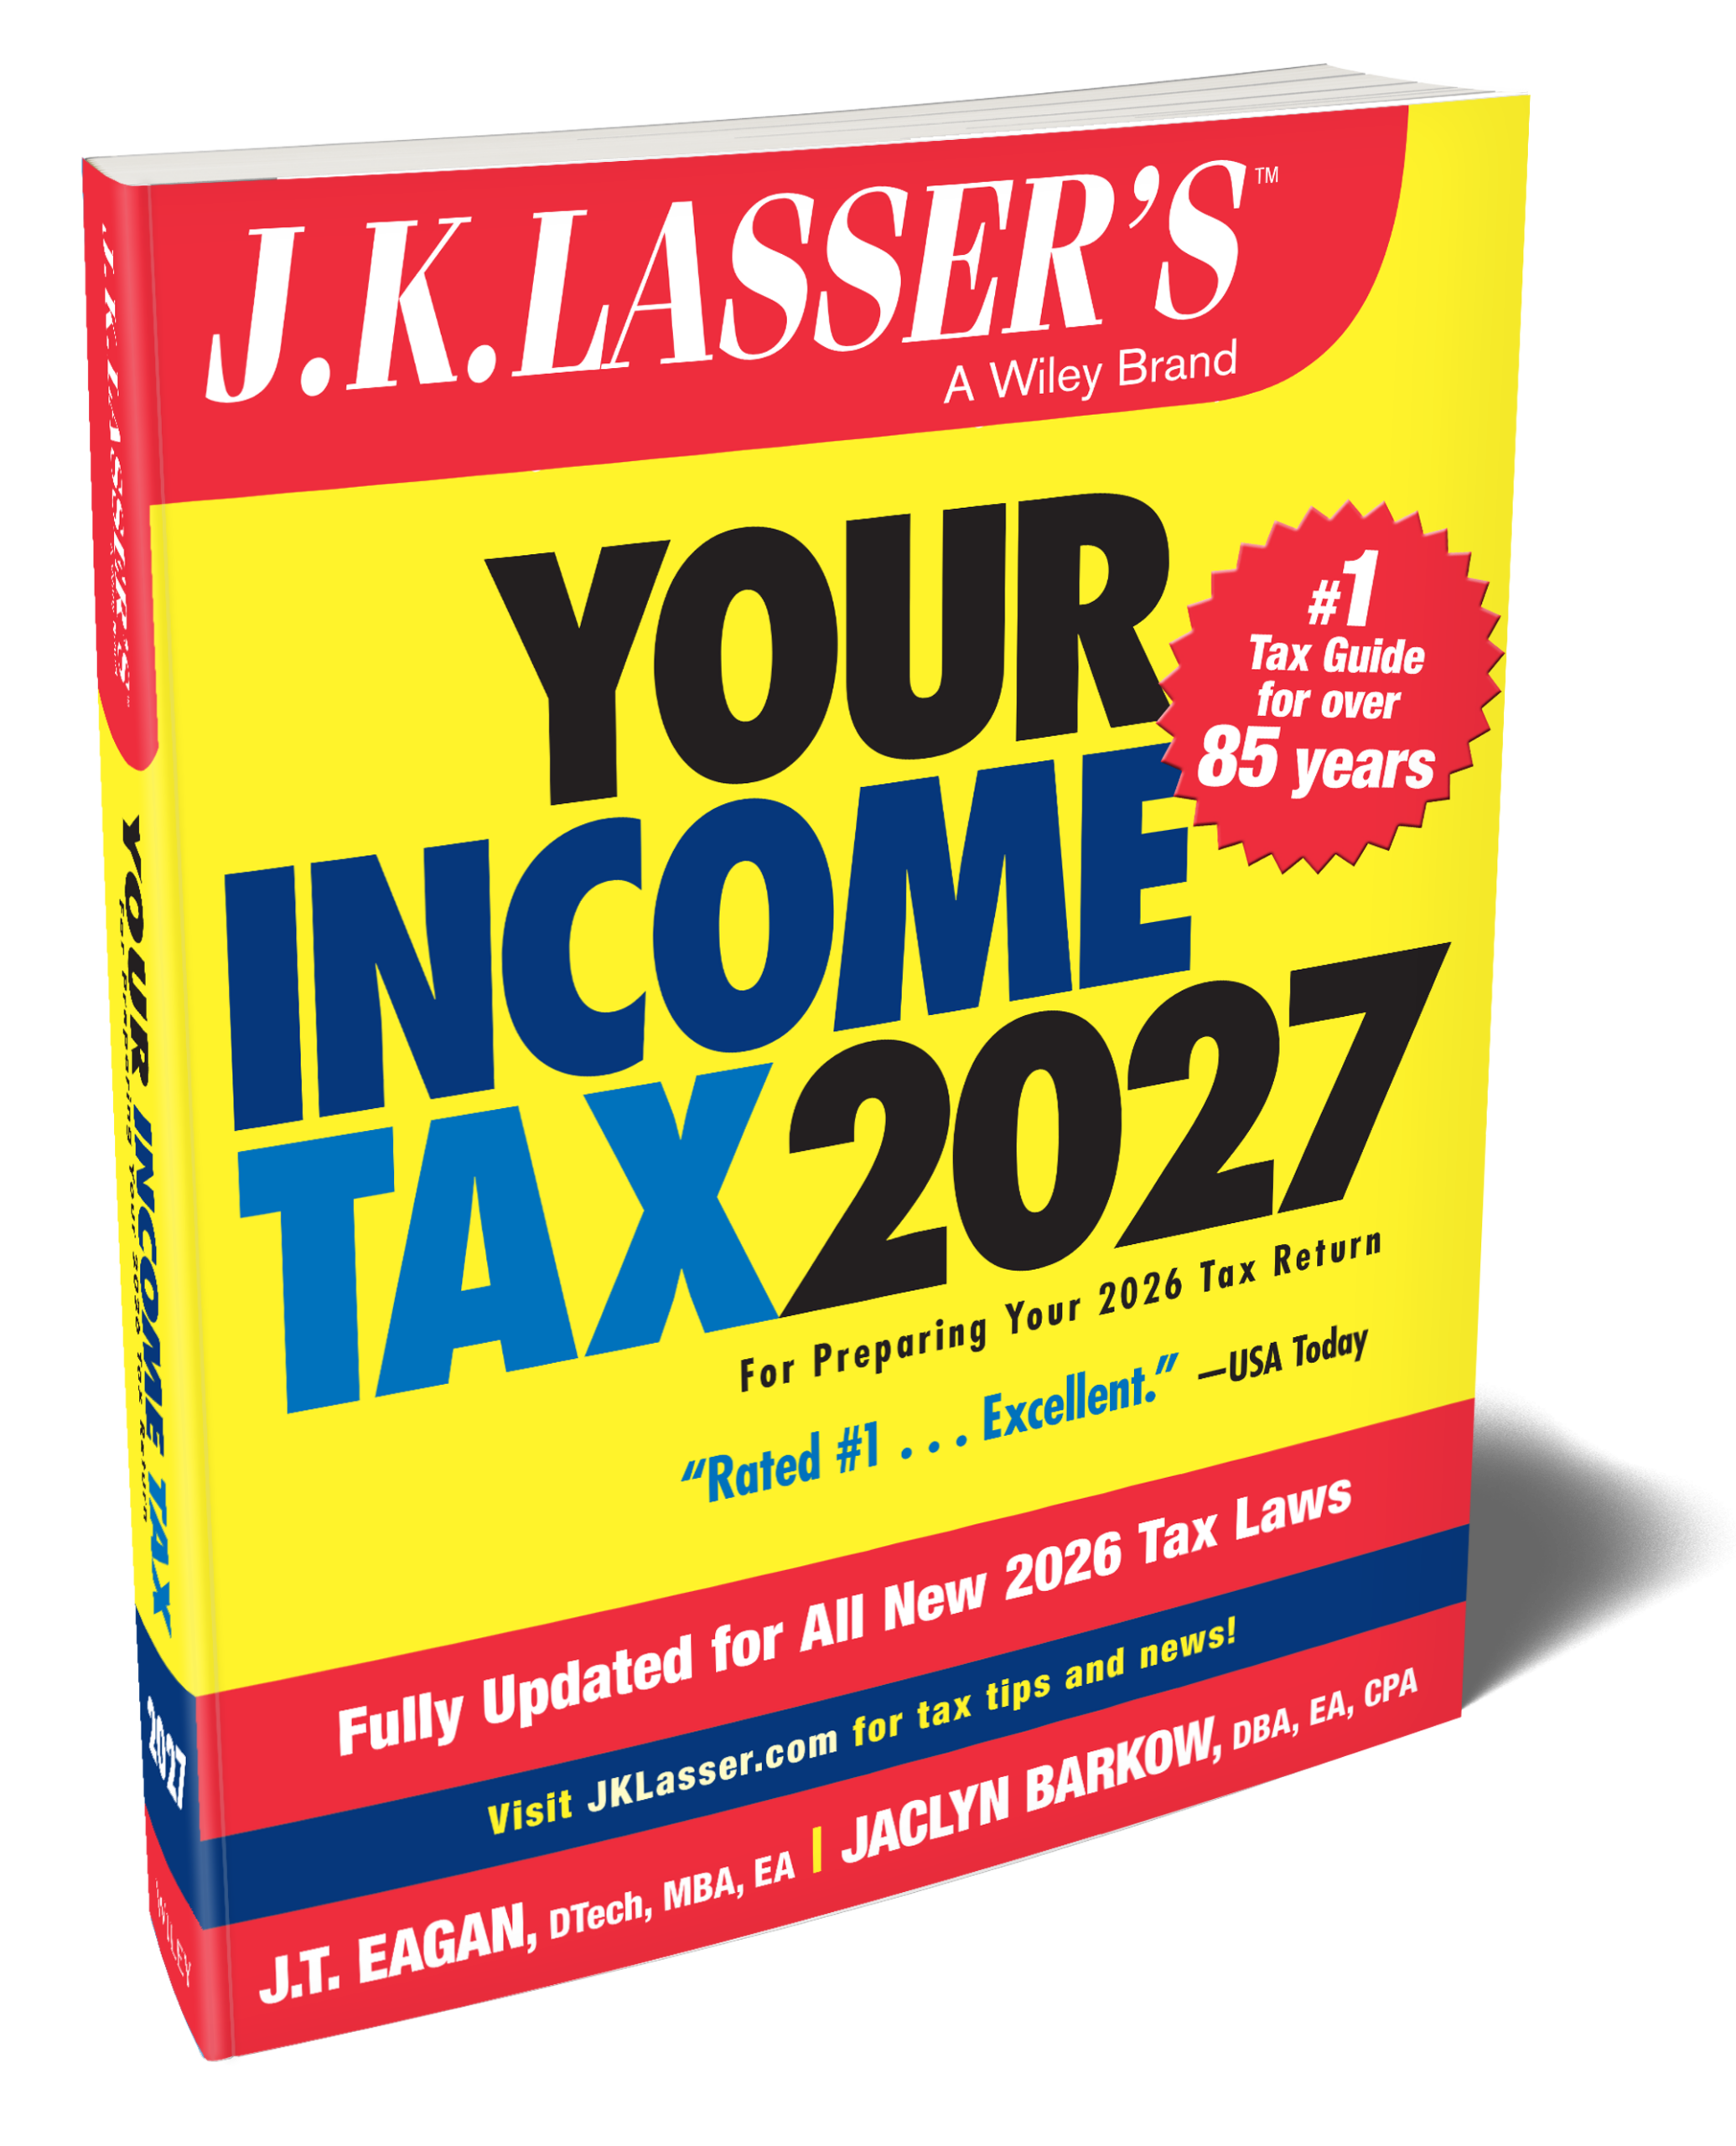
$27.00 
Learn more
Married persons who file separately are barred from claiming certain tax credits, such as the adoption credit or education credits. However, there is no such bar for the low-income housing credit.
In 2007, up to $85,700 of foreign earned income is exempt from tax if a foreign residence or physical presence test is met.
Copyright © 2000- John Wiley & Sons, Inc., or related companies. All rights reserved. Please read our Privacy Policy.