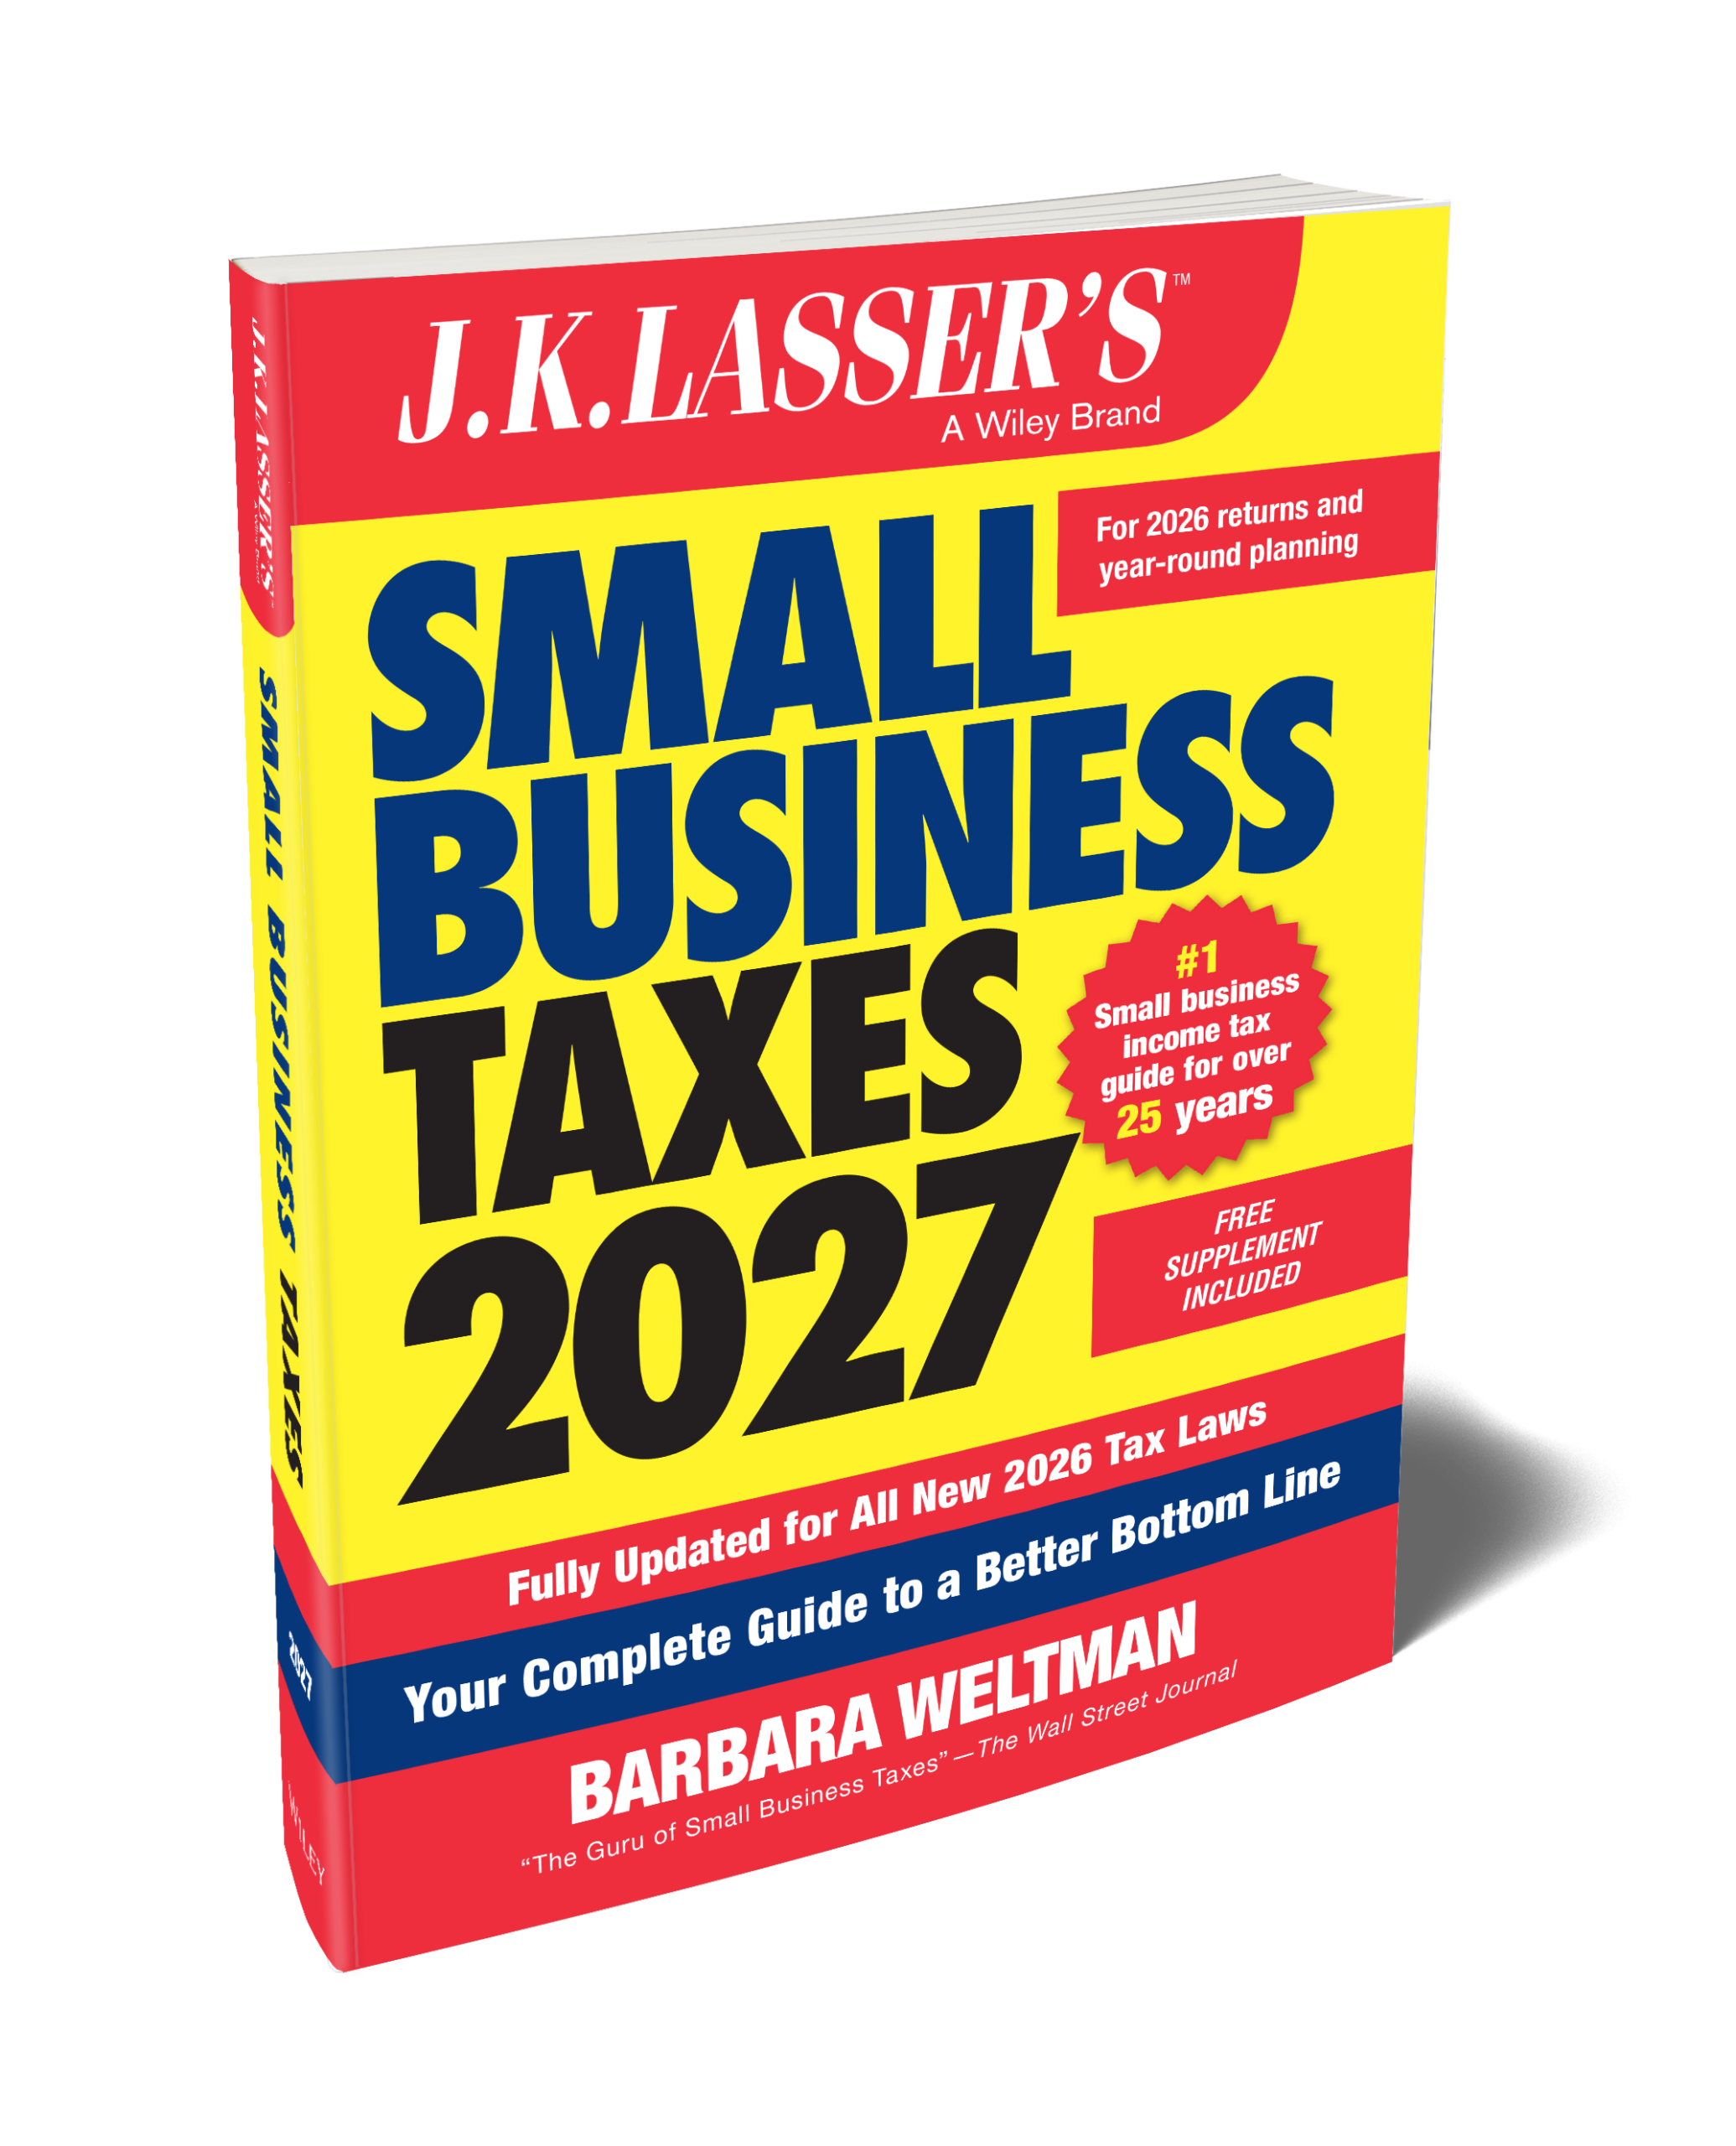
$25.00 
Learn more
An offer in compromise (OIC) is an agreement between a taxpayer and the IRS that settles a taxpayer’s tax liabilities for less than the full amount owed. Taxpayers who can fully pay the liabilities through an installment agreement or other means generally won’t qualify for an OIC. Individuals and businesses that want to submit an offer in compromise should use the 2022 edition of Form 656 booklet. It contains all the necessary forms to submit an offer. If you’re thinking about submitting one, check out the IRS’s Offer in Compromise Pre-Qualifier Tool to determine your eligibility.
A retirement plan that meets tax law tests and allows for tax deferment and tax-free accumulation of income until benefits are withdrawn. Pension, profit-sharing, stock bonus, employee stock ownership, and Keogh plans and IRAs may be qualified plans.
Copyright © 2000- John Wiley & Sons, Inc., or related companies. All rights reserved. Please read our Privacy Policy.